

“Too Obvious a Trick” – Hanwha Aerospace
Recently, discussions about revising the Inheritance and Gift Tax Act—let’s just call it “IGT” for short—have been actively taking place. As we enter a super-aging society, intergenerational transfers of wealth are increasing, and for younger generations, opportunities to acquire a significant sum of money outside of inheritance or gifts are dwindling. From a tax practitioner’s perspective, the current IGT Act has far more complex and extensive regulations regarding gift tax than inheritance tax. Regulations such as “insider transactions” and “unfair advantage transfers” fall under this category.
As you might have easily guessed, most of these regulations were introduced to tax indirect intergenerational wealth transfers, particularly among conglomerates and the wealthy. These regulations were often introduced after someone had already exploited a loophole. When one regulation is established, new methods are devised, which then lead to another regulation, creating an endless cycle. As a result, the number of provisions continues to grow.
To address this, the IGT Act has adopted a “comprehensive taxation principle,” meaning that any direct or indirect method of acquiring another person’s financial benefits without compensation is considered a taxable gift. I personally oppose this regulation. While it is fair to criticize the tax-saving and tax-evading tactics of the wealthy and conglomerates, undermining the fundamental principle of legality in taxation could lead to even greater adverse effects.
Hanwha’s Sudden Capital Increase
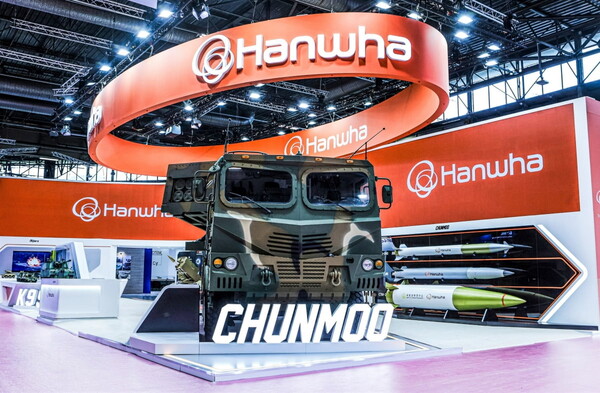
On the 26th, Hanwha Corp., the holding company of Hanwha Group, announced its participation in Hanwha Aerospace’s paid-in capital increase, subscribing to 1,620,297 newly issued shares—corresponding to its 33.95% stake—at a total cost of 980.3 billion KRW.
This announcement reminded me of my concerns about the recently proposed corporate law amendments. Strengthening fiduciary duties of directors not only to the company but also to shareholders, limiting major shareholders’ voting rights in key management decisions (such as mergers or spin-offs), and mandating cumulative voting in director elections are all well-intentioned measures aimed at empowering minority shareholders. However, they could also be exploited by hedge funds or activist investors, leading to excessive litigation and potentially hindering companies from making swift decisions—especially regarding bold investments and innovation.
Capital Increase as a Means of Cashing Out for Hanwha’s Controlling Family
However, after witnessing Hanwha Aerospace’s sudden 3.6 trillion KRW ($2.75 billion) paid-in capital increase, I started to feel that stronger institutional measures to protect minority shareholders are inevitable. The same concern arose when Samsung SDI recently pursued a capital increase.
Hanwha Aerospace justified the move by citing “expanding defense exports, increasing production capacity, and pursuing global M&As” as the primary objectives. They pointed to growing defense demands in Europe and NATO, emphasizing the long-term growth potential of the defense sector. However, investors reacted differently.
Immediately after the announcement, Hanwha Aerospace’s stock plunged over 13%, falling from a record high of 750,000 KRW per share to the low 600,000 KRW range. Although a slight rebound followed when executives from the controlling family began buying back shares, market trust had already been damaged.
This was a sudden and massive capital increase, announced just after the stock hit a historic peak. If the sole purpose was fundraising, Hanwha had many alternative methods, including selling treasury shares, borrowing, or seeking government support. The decision to proceed with a dilutive rights issue raised suspicions about its true intent.
Just before the capital increase, Hanwha Aerospace purchased a 1.3 trillion KRW ($1 billion) stake in Hanwha Ocean (formerly Daewoo Shipbuilding & Marine Engineering), which Hanwha Group had acquired as its shipbuilding subsidiary. The issue? The sellers were Hanwha Energy and Hanwha Impact—two unlisted companies fully owned by the controlling family.
Essentially, Hanwha Aerospace used funds from a publicly traded company to buy overvalued shares from privately held entities owned by the controlling family. Then, to refill its coffers, it carried out a massive capital increase in the open market. Investors quickly interpreted this as a scheme to liquidate assets for the controlling family’s benefit.
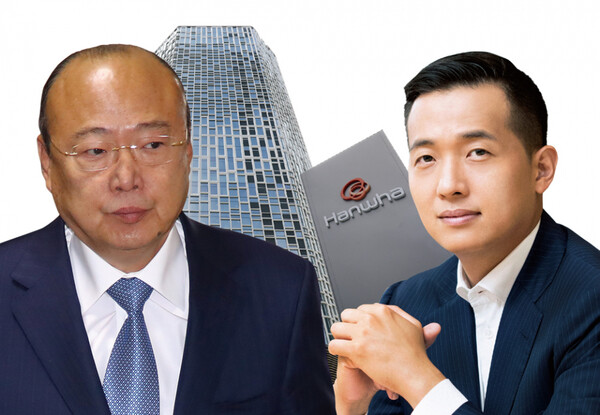
Hanwha Group has already solidified its succession plan around Chairman Kim Seung-yeon’s eldest son, Vice Chairman Kim Dong-kwan. Securing additional shares in the holding company, Hanwha Corp., is crucial for this transition. However, acquiring these shares requires vast sums of cash—potentially reaching several trillion KRW.
Given the current shareholding structure, Kim Dong-kwan and the controlling family need to personally purchase Hanwha Corp. shares in cash. This latest capital increase appears to be a strategic move to generate some of that needed liquidity.
“Doing It So Openly!”
Honestly, this move was so blatant that I was taken aback. The sheer audacity of “pushing this through so openly” almost makes me admire their boldness. We have seen this playbook before—Samsung C&T and Cheil Industries’ merger, LG Chem’s spinoff of LG Energy Solution, SK Innovation’s separation of SK On, and more recently, Doosan Bobcat’s merger with Doosan Robotics. These moves all share a common theme: sacrificing the interests of minority shareholders to benefit the controlling family or major shareholders, while executing succession plans without using their own money.
Looking at how Hanwha Aerospace’s stock price plummeted by over 13% following the capital increase announcement, it seems that even retail investors with limited financial expertise felt that “this is just too much.” The stock prices of affiliated companies also declined in response. Such a market backlash could serve as a warning sign.
Companies that repeat these tricks to benefit their controlling families inevitably suffer from brand damage, stock undervaluation, and capital outflows from foreign and institutional investors. In the long run, this can harm even the controlling family itself by limiting corporate growth and financing opportunities.
However, relying solely on market forces to correct these issues is insufficient. The information asymmetry is stark. Ordinary retail investors have no way of knowing in advance when a capital increase will be announced or whether there are insider transactions taking place. Meanwhile, controlling families have prior access to such information and can time their mergers or capital increases strategically. By the time stock prices react, it is already too late, leaving small investors helpless.
Moreover, minority shareholders are, by definition, small shareholders. Even if their combined stake exceeds 50%, most are passive investors who do not engage in shareholder meetings. As a result, a controlling family’s 20–30% stake effectively functions as absolute control. No matter how much the market criticizes these actions, without institutional checks, such tricks will keep repeating, reinforcing the fundamental issue of a “tilted playing field.”
A Case That Made Me Support Corporate Law Reform
Ironically, Hanwha Aerospace’s capital increase has become a compelling example of why corporate law reform is necessary.
Hanwha Aerospace announced its capital increase on March 20, 2025. Just a few days earlier, on March 14, Samsung SDI also made a surprise announcement of a 2 trillion KRW capital increase. Coincidentally, these events happened right after the National Assembly passed a corporate law amendment aimed at strengthening minority shareholder protections. The law was about to take effect soon.
As mentioned earlier, the corporate law reform expands directors’ fiduciary duties to include not just the company but also all shareholders, mandates electronic shareholder meetings, restricts major shareholders’ voting rights, and introduces cumulative voting for director elections. Once in force, it will significantly limit major shareholders’ unilateral decision-making and increase the influence of minority shareholders in mergers and capital increases.
Thus, these sudden capital increases appear to be a “last-minute rush”—an attempt to push through ownership restructuring before new legal restrictions take effect. While such moves have deepened investor distrust, they have also clearly demonstrated that without regulatory reforms, controlling families will continue exploiting the system.
While market forces can provide short-term warnings, they alone cannot fix a tilted playing field. To restore trust, we need to strengthen institutional safeguards so that such tactics no longer work. Corporate law reform is a crucial starting point. I support it.
About the Author
Im Bang-jin is a CPA and tax accountant at Daeju Accounting Firm. He previously worked at Samil PwC, handling audits, tax adjustments, due diligence, business diagnostics, and valuations. After working in the U.S. on a professional exchange, he specialized in SOX 404 (internal accounting control systems) and internal control consulting. Since 2008, he has been deeply involved in IFRS (International Financial Reporting Standards) implementation projects and later held key finance roles at KDB Life Insurance and ING Life. Drawing from his expertise in accounting, taxation, corporate restructuring, financial planning, and insurance products, he has published practical guides and lectures to help the general public understand these complex topics.
댓글